
Lloyds Bank World Elite Mastercard: A detailed review of its travel perks and £180 fee
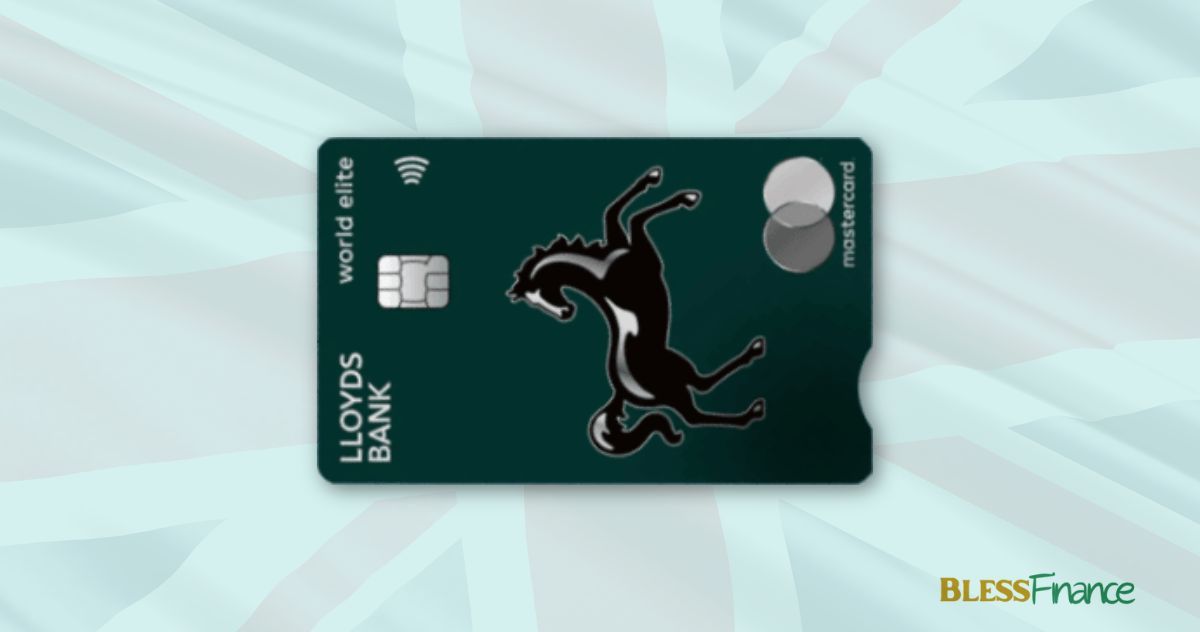
The Lloyds Bank World Elite Mastercard makes a compelling offer with its airport lounge access and fee-free spending abroad. But these premium benefits come with a significant monthly fee and some of the strictest eligibility criteria on the market. This isn’t a credit card for everyone; it’s a specialised tool designed for a very specific type of customer.
This comprehensive review breaks down the numbers behind the £15 monthly cost. We’ll calculate the real-world value of its travel perks, explain the alarmingly high representative APR, and detail the exact requirements you must meet to even be considered. By the end, you will know precisely whether this card is a savvy travel companion or an expensive mistake.
Core Travel Benefits: What You Get for Your Money
This card is built around travel. Its value is almost entirely dependent on how often you find yourself in an airport. The cashback is a secondary feature, not the main attraction.
Airport Lounge Access with Priority Pass
The headline benefit is a complimentary Priority Pass membership, which grants you access to over 1,500 airport lounges globally, no matter your airline or ticket class. With this card, you receive six free lounge passes each year.
These can be used for yourself on six separate trips, or you can bring a guest with you, which would use two passes per trip. Once your six free passes are used up, subsequent visits are charged at a discounted rate, currently £24 per person.
The crucial question is whether this perk justifies the card’s fee. The card costs £15 per month, adding up to £180 annually. A single, pay-as-you-go lounge visit typically costs between £30 and £35. Therefore, your six passes hold a tangible value of at least £180.
The maths is straightforward: if you take three return trips a year with a partner, or six solo trips, the lounge access alone covers the entire annual fee. If you travel less frequently, you are effectively losing money on this feature.
Zero Foreign Transaction Fees
This is arguably the card’s most practical and valuable feature for any traveller. The Lloyds Bank World Elite Mastercard charges no foreign transaction fees on purchases or cash withdrawals made abroad. Most high street bank credit and debit cards impose a non-sterling transaction fee of around 2.95%.
This means that for every £1,000 you spend on hotels, restaurants, or shopping on holiday, you save nearly £30 in fees with this card.
The benefit for cash withdrawals is even more significant. Many cards penalise you twice for taking cash out overseas: a transaction fee plus a separate cash advance fee. This card charges 0% for both, which is an exceptionally rare and valuable perk. However, it’s vital to understand that interest is charged from the moment of withdrawal, a critical detail we’ll cover in the drawbacks section.
The Cashback Programme
While marketed as a feature, the cashback rates are modest and should be viewed as a way to offset the annual fee rather than a primary reason to get the card. The earning structure is tiered:
- You earn 0.5% cashback on the first £15,000 of qualifying spending per year.
- You earn 1.0% cashback on all qualifying spending above £15,000.
Cashback is credited to your account once a year in January. A 0.5% rate is not competitive in the wider market; some free cards offer comparable rates. To put it into perspective, spending £20,000 in a year would earn you £125 in cashback (£75 from the first £15,000 and £50 from the next £5,000). While this is a welcome bonus that reduces your net annual fee to just £55, it’s not a compelling rewards programme on its own.
Understanding the Fees and Charges
The card’s fee structure requires careful attention, particularly the representative APR, which can be misleading if not properly understood.
- Monthly Fee: £15, which equates to £180 per year.
- Representative APR: 54.7% APR (variable). This figure is legally required to include the annual fee in its calculation.
- Standard Purchase Rate: 22.95% p.a. (variable). This is the actual interest rate you will pay on purchases if you do not clear your balance in full.
- Foreign Transaction Fee: 0% on both purchases and cash withdrawals.
- UK Cash Advance Fee: 3% (minimum £3).
- Late Payment Fee: £12.
The Major Drawbacks to Consider
While the benefits are clear, the card’s disadvantages are significant and make it unsuitable for most people. You must weigh these carefully before applying.
- The £180 Annual Fee: This is a pay-to-use card. As demonstrated, its value is directly linked to your travel habits. If you don’t use the six lounge passes, you are paying a hefty sum for benefits you could get elsewhere for free. You must be a frequent traveller to make this fee worthwhile.
- The Misleading 54.7% APR: Seeing an APR over 50% is understandably alarming. However, this “Representative APR” is a legally mandated calculation that assumes a user borrows £1,200 for a year and includes the £180 annual fee. The real interest rate on purchases is 22.95% p.a. (variable). While lower, this is still a high rate, reinforcing a golden rule: this card is for spending and clearing in full each month, not for borrowing.
- Extremely Strict Eligibility: This is the biggest barrier. This is an exclusive product for established, high-earning Lloyds Bank customers. You must hold a specific premium current account *and* meet a high income or savings threshold. We detail these rules in the next section.
- The Cash Withdrawal Interest Trap: While Lloyds waives the *fee* for foreign cash withdrawals, they do not waive the *interest*. Interest at 22.95% APR begins to accrue from the very day you withdraw the cash, with no interest-free period. This feature is for small, emergency cash needs and should be paid back immediately via your banking app to minimise costs.
- Weak Cashback Rate: At a starting rate of 0.5%, the cashback is underwhelming for a premium card. It serves only to soften the blow of the annual fee, not as a primary reward.
Who is Eligible for This Card?
The eligibility criteria for the Lloyds Bank World Elite Mastercard are rigid and non-negotiable. Do not apply unless you meet all of the following conditions.
You must:
- Be 18 or over and a permanent UK resident.
- Have a good credit history, free from recent defaults or County Court Judgements (CCJs).
- Be an existing Lloyds Bank customer holding a Club Lloyds, Premier, or Private Banking current account.
- Have a minimum annual income of £50,000, OR have at least £25,000 in savings or investments held with Lloyds Bank.
How to Apply
If you meet the stringent criteria, the application process is designed to be safe and straightforward, beginning with a soft eligibility check that will not impact your credit score.
- Be a Premium Customer: You must already have one of the required Lloyds Bank current accounts before you can even consider applying for the card.
- Use the Eligibility Checker: Navigate to the Lloyds Bank World Elite Mastercard page on the bank’s official website and use their “Check your eligibility” tool.
- Complete the Soft Search: This initial check will confirm your details and tell you if you’re likely to be accepted. This step does not leave a mark on your credit file.
- Proceed to Full Application: Only if the eligibility checker gives you a positive result should you continue to the full application. This final step is the only part of the process that will register a “hard search” on your credit report.
How It Compares to Other Travel Cards
To understand its place in the market, it’s useful to compare the Lloyds card against a leading free option and a top-tier premium alternative.
vs. The Barclaycard Rewards Card (Free Option)
The main difference here is the lounge access. The Barclaycard Rewards card also offers 0% fees on spending and cash withdrawals abroad, making it a direct competitor on core travel functionality. However, it has no annual fee and offers a flat 0.25% cashback.
The choice is simple: if you value six lounge passes at £180, the Lloyds card is superior. If you don’t need lounge access, the Barclaycard Rewards card provides the essential travel benefits for free.
vs. The American Express Platinum Card (Premium Option)
This comparison highlights the Lloyds card’s position as a “premium-lite” product. The Amex Platinum card has a much higher annual fee (around £650) but offers a far more extensive benefits package, including unlimited lounge access for you and a guest, comprehensive travel insurance, hotel status, and dining credits.
However, it’s poor for spending abroad, with a 2.99% foreign transaction fee. The Lloyds card is for the savvy, cost-conscious premium traveller, while the Amex Platinum is for those seeking ultimate luxury without budget constraints.
Final Verdict: Is the Lloyds Bank World Elite Mastercard for You?
This is a niche card with a clearly defined purpose and audience. Its value is entirely conditional on your travel patterns and your existing relationship with Lloyds Bank.
This Card is an Excellent Choice For:
- Existing Premium Lloyds Customers: You must already meet the strict account and income/savings requirements to be eligible.
- Frequent Travellers: You fly often enough to use all six lounge passes each year, thereby making the £180 annual fee pay for itself.
- Disciplined Spenders: You have the financial habit of paying your credit card balance in full every month without fail, avoiding the high interest charges.
You Should Avoid This Card If:
- You Are Not an Eligible Lloyds Customer: The vast majority of people will be ruled out by the strict eligibility criteria.
- You Travel Infrequently: If you only take one or two trips a year, you are better off with a no-fee travel card and paying for lounge access ad-hoc if needed.
- You Tend to Carry a Balance: The 22.95% purchase rate will quickly eliminate any value gained from the rewards and perks. This card is not suitable for borrowing.
In conclusion, for the small group of high-earning, frequently travelling Lloyds Bank customers, this card offers outstanding value. The fee is fairly priced against the lounge access benefit, and the fee-free foreign spending is a top-tier perk. For this specific user, it’s a superb travel tool. For everyone else, there are far more suitable and accessible options available.
About the author




